2026 brings a wave of new legislation on insurance, tax and accounting, and public investment, much of it effective from 1 July 2026. APA’s professional team has summarised what businesses, project owners and project management units should review in Q4/2026.
1. Social insurance, health insurance and labour
- Base salary of VND 2.53 million/month from 1 July 2026 (Decree 161/2026/ND-CP). Amounts linked to it change accordingly: a one-off childbirth allowance of VND 5.06 million per child; a funeral allowance of VND 25.3 million; health insurance covers 100% of a visit costing less than VND 379,500.
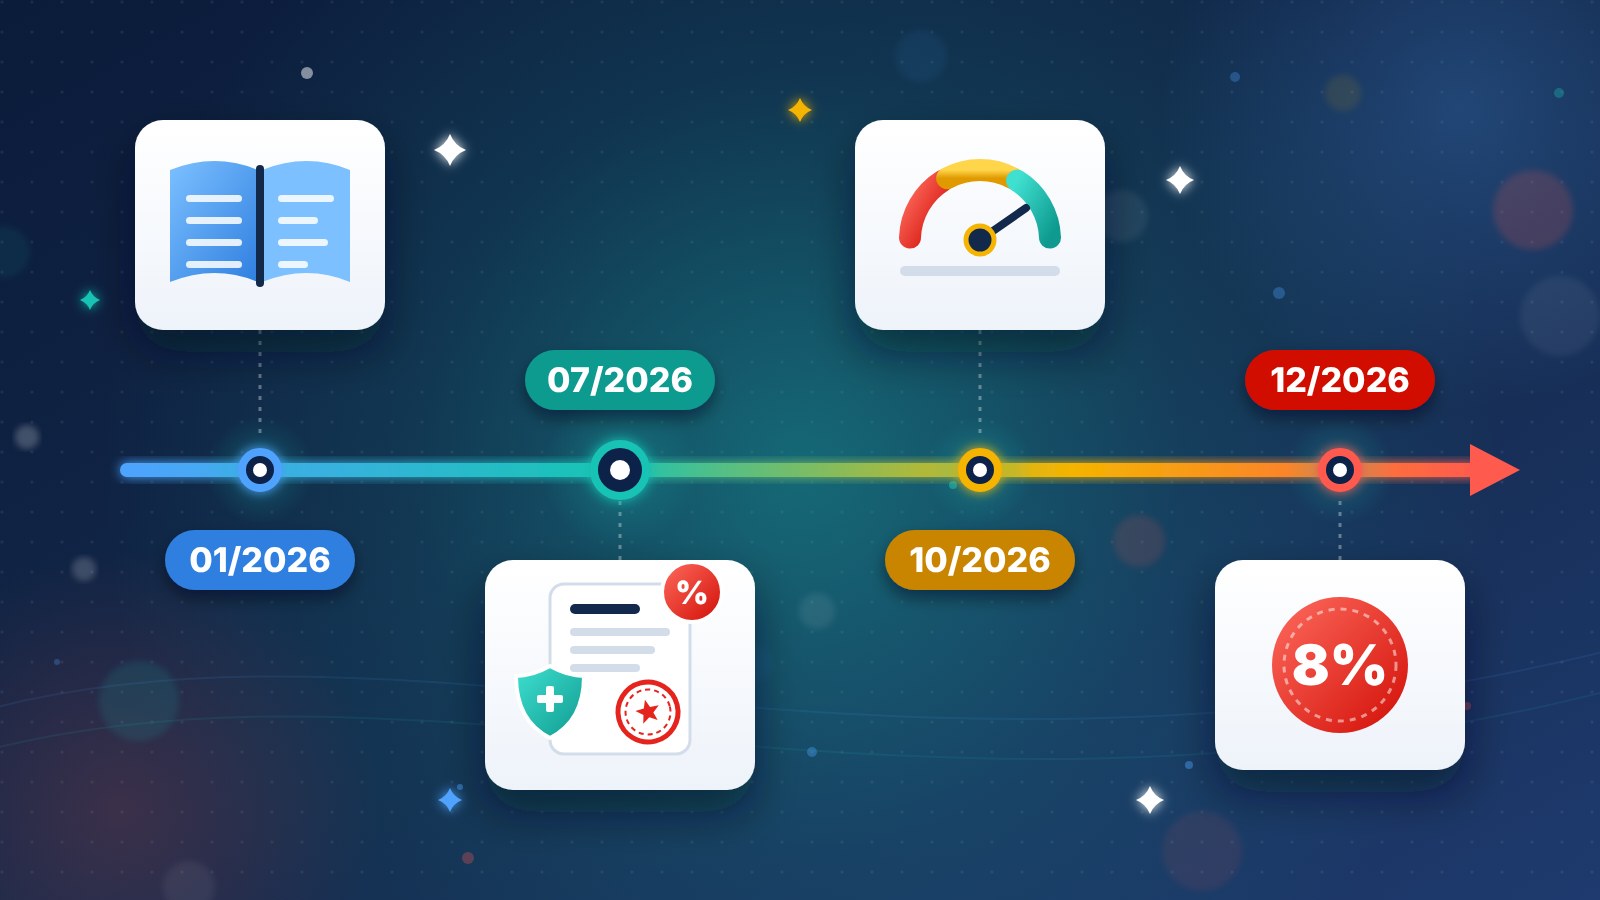
- Pensions and social insurance allowances rise by 8% (Decree 162/2026/ND-CP); recipients whose adjusted amount is VND 3.5 million or less receive an extra VND 300,000/month.
- The amended Health Insurance Law took effect on 1 July 2026; patients with 62 diseases or disease groups listed in Circular 01/2025/TT-BYT may go directly to specialised facilities with full benefits.
- The Social Insurance Law No. 41/2024/QH15 (effective 1 July 2025) remains an inspection focus: employees with contracts of one month or more and registered household-business owners are subject to compulsory social insurance under the roadmap; the minimum contribution period for a pension is now 15 years.
- From 1 October 2026, Circular 17/2026/TT-BNV sets unit prices for public services financed by the Unemployment Insurance Fund.
What businesses should do: review short-term contracts, collaborators and allowances included in the insured salary; update health insurance contributions and allowances to the new base salary.
2. Tax and accounting
- The Tax Administration Law No. 108/2025/QH15 takes effect on 1 July 2026: household businesses self-declare and pay by period instead of the presumptive (lump-sum) regime; e-commerce platform operators withhold and pay on sellers’ behalf; refunds, exemptions and reductions are automated based on data and risk management; the period for amending returns is 5 years.
- The amended Personal Income Tax Law (effective 1 July 2026): family deductions of VND 15.5 million/month for the taxpayer and VND 6.2 million/month per dependant, applicable from the 2026 tax year; the progressive schedule is cut from 7 to 5 brackets (5%–35%).
- The VAT reduction to 8% continues until 31 December 2026 for eligible goods and services (Resolution 204/2025/QH15, Decree 174/2025/ND-CP).
- Circular 99/2025/TT-BTC replaces Circular 200/2014/TT-BTC from 1 January 2026: companies may design their own vouchers, accounts and ledgers but must issue an internal accounting policy; minimum requirements for accounting software apply for the first time; annual financial statements are due within 90 days.
- Decree 255/2026/ND-CP on related-party transactions applies from the 2026 CIT period: the revenue threshold for exemption from transfer pricing documentation rises to under VND 500 billion, but related-party disclosures are still required.
3. Management, payment and settlement of public investment
- Decree 193/2026/ND-CP (effective 1 July 2026) governs settlement of project investment capital; Article 20 sets fee norms for independent audits and settlement verification. Circular 73/2026/TT-BTC issues forms 01–12/QTDA. Projects that submitted dossiers before 1 July 2026 continue under Decree 254/2025/ND-CP.
- The Construction Law No. 135/2025/QH15 and decrees on construction investment costs and contracts took effect on 1 July 2026.
- Decree 349/2026/ND-CP (9 September 2026), amending Decree 214/2025/ND-CP, raises the direct-appointment threshold for consulting packages to VND 3 billion (previously VND 800 million); procurement packages up to VND 100 million may be decided by the head of the unit. The shortened direct-appointment procedure has 8 steps, with the draft contract and results published on the National e-Procurement System.
- Decision 1129/QD-TTg (24 June 2026): official scoring of public investment disbursement for ministries, agencies and localities from the October 2026 reporting period.
- As of 30 September 2026, the country had disbursed VND 642,961.6 billion, or 64.8% of the plan assigned by the Prime Minister (excluding 5% of local capital reserved for the Lào Cai – Hanoi – Hải Phòng railway).
APA’s recommendations
Businesses should finalise payroll and social insurance policies, an internal accounting policy under Circular 99 and transfer pricing documentation before the 2026 year-end close. Project owners should prepare the audit package estimate under Article 20 of Decree 193/2026/ND-CP now and use the new direct-appointment threshold to shorten settlement time. APA offers a free initial document review – call 0983 927 536.
Legal references
- Law on Social Insurance No. 41/2024/QH15
- Law amending and supplementing certain articles of the Law on Health Insurance
- Decree No. 161/2026/ND-CP – on the statutory base salary
- Decree No. 162/2026/ND-CP – adjusting pensions and social insurance allowances
- Circular No. 01/2025/TT-BYT – guiding the implementation of health insurance
- Circular No. 17/2026/TT-BNV – unit prices of public services funded by the Unemployment Insurance Fund
- Law on Tax Administration No. 108/2025/QH15
- Law on Personal Income Tax (amended), 2025
- National Assembly Resolution No. 204/2025/QH15 – on value-added tax reduction
- Decree No. 174/2025/ND-CP – on value-added tax reduction policy
- Circular No. 99/2025/TT-BTC – guiding the corporate accounting regime
- Decree No. 255/2026/ND-CP – on tax administration for enterprises with related-party transactions
- Decree No. 193/2026/ND-CP – on project investment capital settlement
- Decree No. 254/2025/ND-CP
- Circular No. 73/2026/TT-BTC – project settlement report forms
- Law on Construction No. 135/2025/QH15
- Decree No. 214/2025/ND-CP – guiding the Law on Bidding on contractor selection
- Decree No. 349/2026/ND-CP – amending Decree No. 214/2025/ND-CP
- Prime Minister’s Decision No. 1129/QD-TTg – on scoring public investment disbursement