Vietnam’s 2026 public investment plan exceeds VND 1 quadrillion (VND 1 million billion). At the national conference on 24 April 2026, the Prime Minister required disbursement results to be a key criterion for evaluating officials under Regulation 366-QD/TW, leaders to be assigned to each project, and weak PMUs, consultants and contractors to be replaced. As of 30 September 2026, the country had disbursed 64.8% of the plan; 27 central agencies and 15 localities were still below the national average.
1. The scoring framework under Decision 1129/QD-TTg
Decision 1129/QD-TTg of 24 June 2026 approved the disbursement scoring scheme; it was piloted for July–September and applies officially from the October 2026 reporting period. Scores are calculated automatically on the national financial database and published on the Ministry of Finance and Government portals.
| Period | Criterion | Points |
|---|---|---|
| Monthly (100 points) | Cumulative disbursement rate vs. the national average | 45 |
| Disbursement in the month vs. the registered amount | 45 | |
| Compliance with reporting on the system | 10 | |
| Annual (100 points) | Disbursement rate vs. the Prime Minister’s target | 90 |
| Compliance with reporting | 10 |
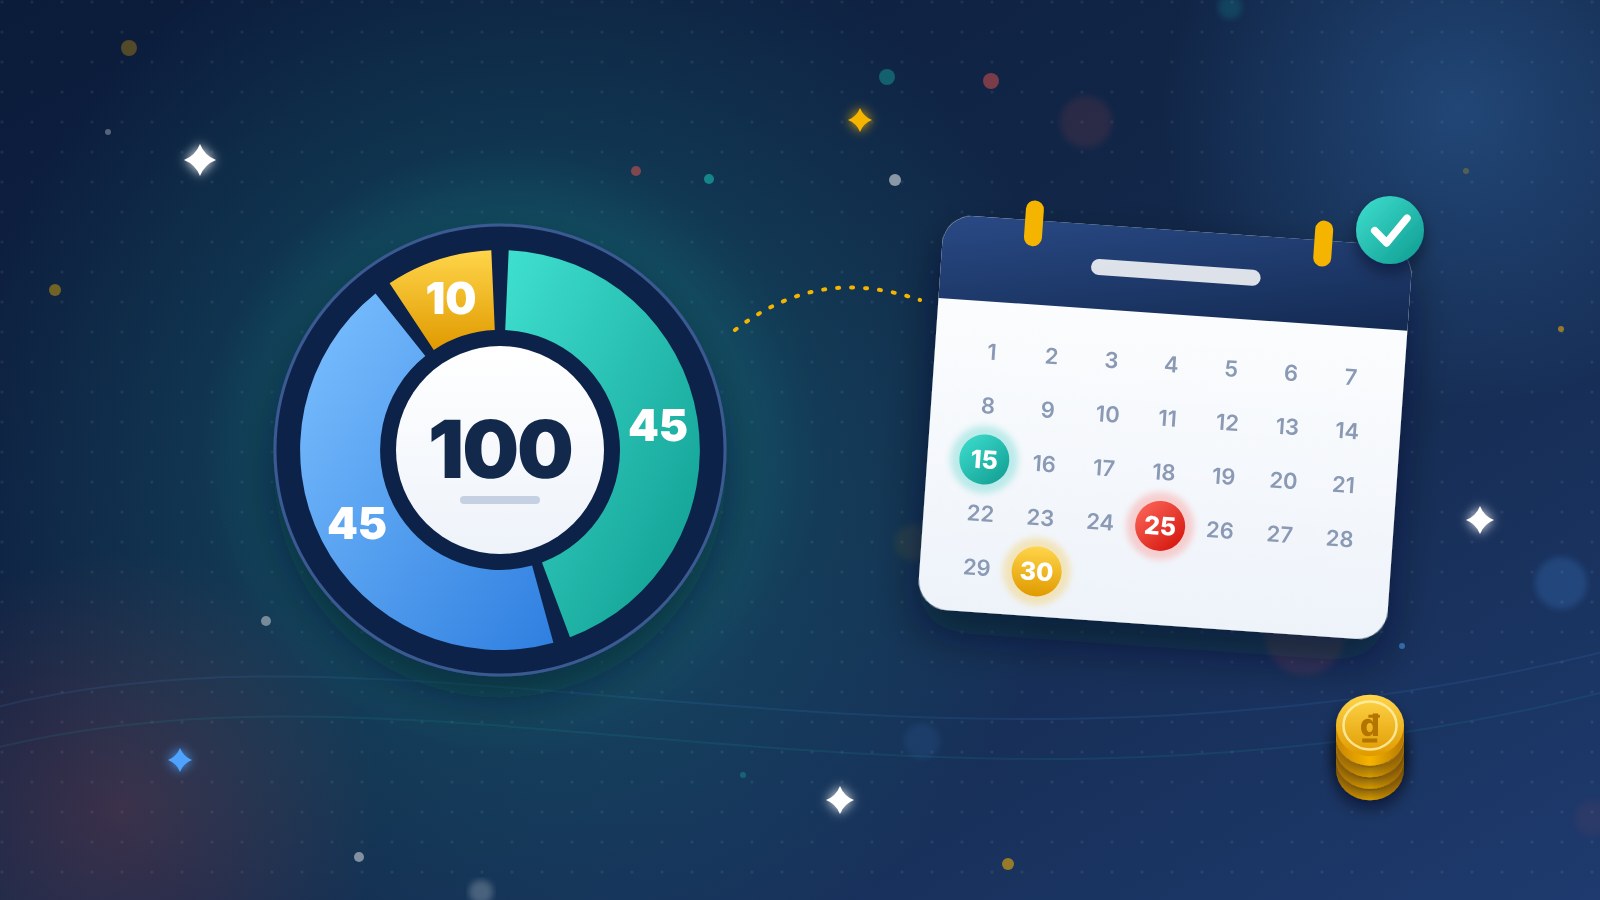
Data deadlines: the monthly disbursement plan by midnight on the 15th; obstacles and difficulties by midnight on the 25th; local budget payment data within 2 days after month-end. The 13-month annual result is used to assess and rank collectives and individuals.
2. From provincial targets to KPIs for project owners’ heads
Many provinces cascade targets down to each project owner. Quảng Ngãi, for example, scores KPIs from October 2026, requires every project owner to exceed the national average by 31 October 2026 and asks its Department of Home Affairs to assess heads of units with low rates. To stay ahead, APA suggests an internal KPI set combining outcome and leading indicators:
| Group | Suggested KPI | Measure |
|---|---|---|
| Outcome | Cumulative disbursement rate | Disbursed / allocated capital; vs. national average and annual target |
| Outcome | Monthly plan achievement | Actual disbursement / amount registered for the month |
| Leading | Speed of detailed capital allocation | Days from assignment to detailed allocation |
| Leading | Accepted work awaiting payment | Value accepted but not yet submitted to the Treasury |
| Leading | Payment file processing time | Days from contractor submission to Treasury submission |
| Leading | Outstanding advances | Overdue advance balances under contracts |
| Compliance | On-time reporting | Periods updated by the 15th, 25th and month-end |
| Compliance | Timely settlement of completed projects | Projects submitting settlement files on time under Decree 193/2026/ND-CP |
3. Pitfalls to avoid
- Registering low monthly plans to score well: the Ministry of Finance found units scoring highly on monthly plans while actual disbursement stayed below average, and will adjust scoring from October 2026.
- Large advances to “boost the numbers”: these raise the risk of unrecovered advances and disallowed costs at audit and settlement.
- Year-end rush: paying for work without complete acceptance records is a common error found in settlement audits.
How APA can help
APA’s digital audit platform reads Treasury-approved vouchers directly, tracks cumulative payments and advances by contract and flags missing or out-of-sequence documents. Our settlement advisory and investment cost control services give project owners accurate data for each scoring period and shorten the settlement of completed projects.
Legal references
- Prime Minister’s Decision No. 1129/QD-TTg – on scoring public investment disbursement
- Politburo Regulation No. 366-QD/TW – on reviewing, assessing and grading collectives and individuals in the political system
- Law on Public Investment No. 58/2024/QH15
- Decree No. 193/2026/ND-CP – on project investment capital settlement